Home/Commercial/Capabilities/COI and insurance
Licensed and insured furniture repair
Insured, and named on your certificate.
A New York managing agent checks one thing: whether the building, the owner and the agent are named on the policy. We issue certificates to the requirement in your own rider, with the endorsements attached, before a technician is ever scheduled.
Three words
Licensed and insured furniture repair means three different things.
Most contractors can claim the first two. Buildings check the third.
- Word oneLicensed
A registered business in good standing, under the name on the contract and the invoice. In NYC furniture repair is not a licensed trade, so the word describes the company.
- Proves
- A real, filed entity stands behind the quote.
- Does not prove
- Who pays if solvent goes over on a stone floor.
- Word twoInsured
Live policies: general liability, workers' compensation, commercial auto, and excess cover above them. Most contractors have this part.
- Proves
- A carrier stands behind the work.
- Does not prove
- That the cover reaches you. By default a policy protects only its own insured.
- Word three, the one that gets checkedNamed
Your ownership entity, managing agent and any net lessee written onto the certificate as additional insureds, with the endorsement forms attached.
- Proves
- Your building can be defended under our policy, not its own.
- Where it fails
- One word spelled differently from the deed. That is a rejected certificate and a lost work window.
The certificate
What a managing agent reads, line by line.
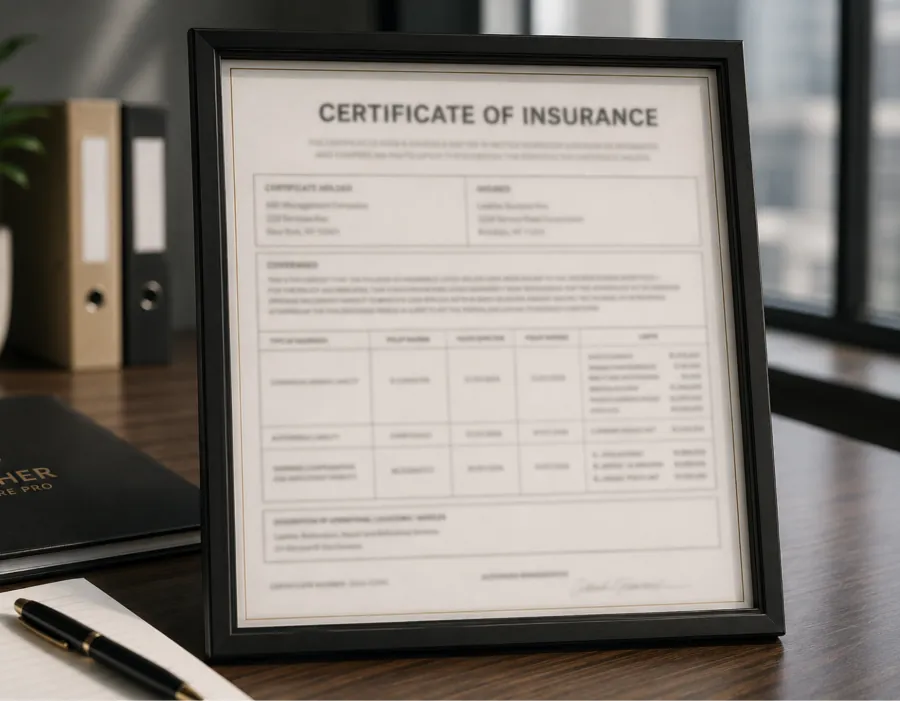
A certificate of insurance is a one-page summary of policies that already exist. Every box on it is a reason to send it back.
- 01
The insured
Our legal name, exactly as filed and as it appears on the invoice. Bounces when the certificate uses a trading name and your system holds the filed one.
- 02
Certificate holder
Usually an ownership LLC, not the name on the awning. Bounces when it is made out to the street address instead of the entity.
- 03
Additional insured
The names our general liability extends to. Bounces when the box is ticked but no endorsement form is attached behind it.
- 04
Description of operations
The address, floor, work and purchase-order reference. Bounces when it is blank and the dock desk cannot tie it to a visit.
- 05
The coverage grid
Each line and its limit, checked against your rider. Bounces when one limit sits below the figure the rider names.
- 06
Effective and expiry dates
They have to cover every visit, including the last phase. Bounces when a policy renews in the middle of the job.
- 07
Waiver and priority wording
Waiver of subrogation, and primary and non-contributory. Bounces when the rider requires them and the form is silent.
- 08
Producer and carriers
The issuing agency and the carriers behind each line. Bounces when a carrier falls below the rating the rider sets.
Who is named
Getting the names right is most of the job.
A single Manhattan floor can involve four or five entities, each spelled exactly, none of which can be guessed from the address.
- 01Building ownershipAlmost always an LLC with a name nothing like the building's. From the deed name in your rider.
- 02Managing agentNamed alongside ownership, not instead of it. From the agent's own certificate request.
- 03Net lesseeA separate insured party where the building is on a master lease. From the lease's insurance exhibit.
- 04Tenant of recordWhen the seating is inside a leased suite. From your lease or alteration agreement.
- 05Ownership groupPortfolios name the group once, through a property and facility program.
We ask for your insurance requirement before we quote, not after you accept. For licensed and insured furniture repair, the rider is where every name is spelled the way the building will check it, and a requirement above our standing limits is arranged rather than assumed. The rest of the file, W-9, supplier form and portal setup, runs through vendor services.
Coverage
The lines a furniture job actually touches.
Licensed and insured furniture repair has real risks to cover: the work puts solvents, dyes and heat next to carpet, stone and millwork, in rooms people are still using.
- General liabilityInjury and damage to others. The realistic exposure is the floor under the sofa, not the sofa.Every managed property
- Workers' compensationStatutory in New York and New Jersey. Covers a technician hurt on your floor, in your elevator or at your dock.Managing agents, institutions
- Commercial autoThe vans that bring materials in and take pieces out on a pickup and delivery job.Dock-scheduled buildings
- Umbrella and excessSits above the primary lines and lifts the total limit, which is how a high requirement gets met.Class A towers, hotel groups
- NY disability and paid leaveA New York State requirement shown on its own form, asked for alongside workers' compensation.NYC managing agents
We do not publish our limits. A limit only means something against the figure your rider requires. Send the requirement, we confirm each line against it in writing, and if one cannot be met you hear it before the quote.
Rejections
Eight reasons a certificate comes back.
None of them are about insurance. All of them are about how the form was filled in.
- 01
The holder is named wrong
Made out to the street name, not the owner LLC.Avoided bycopying the holder line word for word from the rider.
- 02
A name is missing
Ownership named, managing agent or net lessee left off.Avoided byusing the rider's entity list as a checklist.
- 03
Nothing behind the ticked box
Additional insured marked, no endorsement attached.Avoided bysending the endorsement forms every time.
- 04
Operations left blank
A valid certificate nobody can tie to the visit.Avoided bywriting the address, floor, work and PO in.
- 05
A limit below the rider
A standard certificate sent without reading the requirement.Avoided byreading the rider before quoting.
- 06
The dates stop short
Valid on day one, expired by the last phase.Avoided byre-issuing before renewal, not after.
- 07
No waiver of subrogation
The lease asks for it and the form is silent.Avoided byendorsing it on, then stating it.
- 08
No primary and non-contributory
Your own carrier could be asked to contribute.Avoided byreading the lease exhibit, not the email.
Where the file is read first
Some properties check the paperwork before the quote.
Any business can ask us for a certificate. In these sectors, licensed and insured furniture repair means being on the approved list before the job exists.
 Property managementStanding riders and owner entities that change building by building.
 Corporate officesHigh stated limits, dock schedules and procurement portals.
 HotelsBrand insurance standards for every contractor on site.
 HealthcareFormal vetting, where an expired certificate cancels the visit.
 Real estateModel units and rentals where the agent controls access.
 Event venuesTheir own conditions for every supplier between bookings.
Every other sector gets certificates on the same terms. See all industries.
Questions
What procurement and facilities ask first.
Are you a licensed and insured furniture repair company?
Yes, in all three senses: a filed business under the name on your contract and invoice; live general liability, workers' compensation, commercial auto and excess policies; and your ownership, managing agent and any net lessee named on the certificate as additional insureds, with the endorsements attached.
Can you name our building and managing agent as additional insured?
Yes, and usually more than those two. Send the rider or the agent's own request form and every name is copied from it word for word, since a misspelled entity is the most common rejection there is.
How do we get a certificate of insurance from you?
Send the requirement: the rider, the lease exhibit or the agent's request form. We confirm each line against it in writing, have our agency issue the certificate to the named holder with the endorsements, and confirm the building has accepted it. There is no charge.
What if our required limits are higher than a licensed and insured furniture repair company usually carries?
You hear it before the quote, not after the crew is booked. High requirements are usually met by the excess layer over the primary policies, and where cover has to be arranged, that is confirmed in writing first.
Our certificate expires partway through the contract. Do we chase you?
No. A replacement goes to the same holder, with the same named insureds and endorsements, and is filed before the old one lapses. That matters most on phased work, maintenance and emergency repairs.
Send the requirement
Send us your insurance requirement. We read it before we quote.
Every name is copied from it, every line is checked against it, and the certificate is filed with the building before a date is offered. Licensed and insured furniture repair across Manhattan, Brooklyn, Queens, the Bronx, Staten Island, Long Island and New Jersey.